LET’S TALK ABOUT YOUR CLAIM
Tell us what happened, and we’ll help you understand your options. Without confusing insurance jargon.
Call (727) 422-6389 or fill out our contact form to receive a no obligation claim review.
Share a few details and we’ll be in touch to discuss how we can help.
Storm Damage Guide
Dealing with Storm Damage: Why You Shouldn’t Handle It Alone
When severe weather strikes Florida, fast action is vital to protect your property and your loved ones. But once the immediate danger passes, you face a second storm: a complex, high-stakes insurance claims process. Severe weather causes catastrophic structural losses, and insurance companies often use regional chaos to delay payouts or offer lowball settlements.
You shouldn’t have to fight for your recovery alone while rebuilding your life. A Claims Cafe public adjuster will step in to navigate the corporate bureaucracy, itemize your losses, and fiercely advocate for your fair settlement.
Here’s a suggested list of what you should do immediately following a major weather event, and why having an independent expert in your corner is your best strategy.
The Destructive Perils That Threaten Your Home
Different types of severe weather introduce highly specific structural threats that require unique claims strategies:
- Hurricanes and Tropical Storms: High-velocity winds tear away siding and roofing materials, while torrential rain enters through structural breaches or causes massive localized flooding.
- Tornadoes: Violent, rotating wind columns can instantly lift away roofs, shatter window systems, and throw heavy debris or massive trees directly into walls.
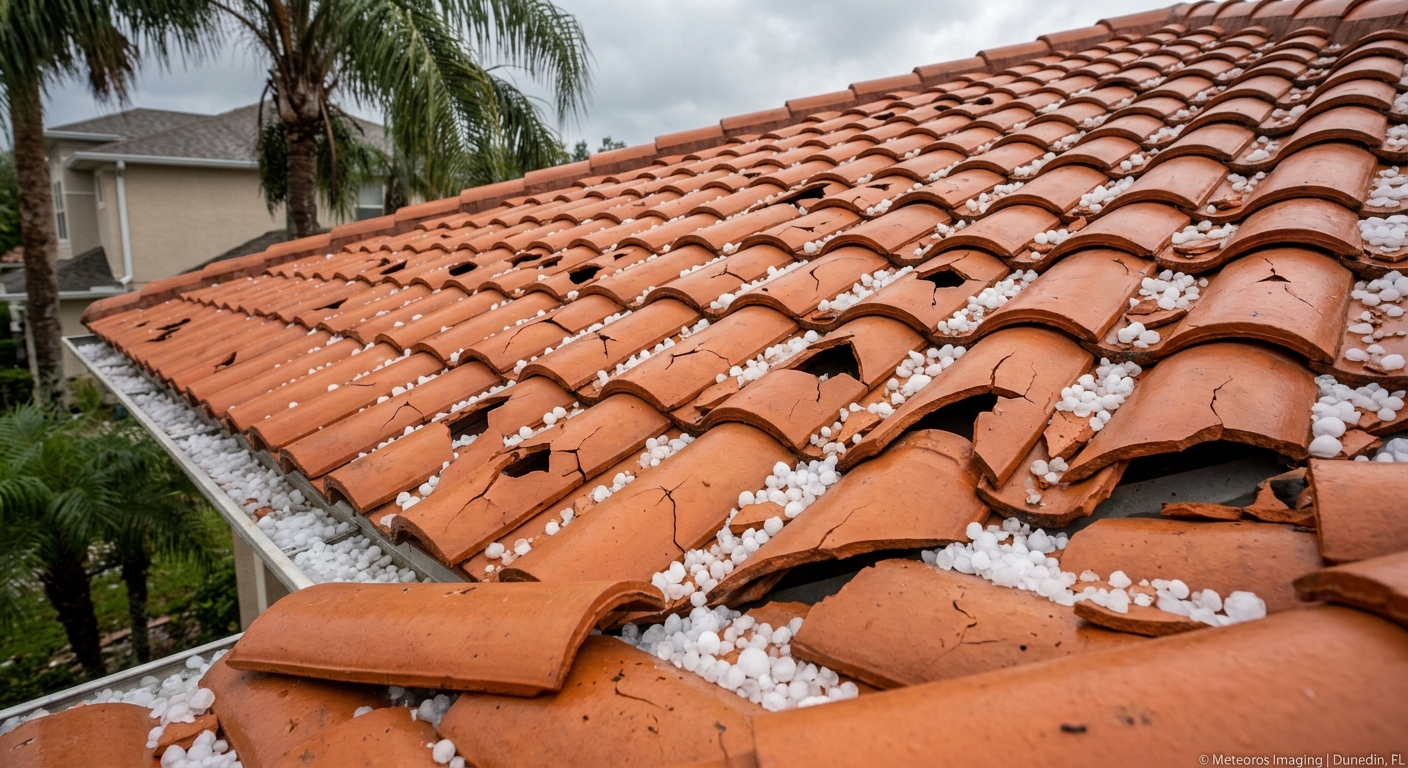
- Hailstorms: Large frozen pellets fracture barrel tiles, bruise asphalt shingles, crack vinyl siding, and smash glass skylights.
- Severe Thunderstorms: Sudden, high-speed straight-line winds uproot heavy timber onto your home, while lightning strikes cause sudden fires or fry internal electrical systems.
- Winter Storms: While unusual in Florida, freezes create ice dams in gutters, stress roofing systems with heavy weight, and cause indoor water lines to freeze and burst.
Ensure Safety First
Before you step outside to check the exterior of your home, make sure the environment is entirely stable.
- Watch for hidden hazards: Steer clear of downed power lines, standing puddles that could be electrified, and sagging ceilings.
- Evacuate for major threats: If you smell gas, notice a shifted foundation, or hear structural creaking, leave the property immediately and call emergency services.
The Claims Cafe Advantage: A catastrophic storm site is highly volatile. We help you identify immediate safety threats from a distance, ensuring you don’t expose your family to physical danger just to check on property damage.
Document the Destruction Extensively
Insurance companies rely heavily on proof that a specific weather event, and not ordinary wear and tear, caused your losses. Do not touch or clean anything until you have thorough visual evidence.
- Take hundreds of photos and videos: Capture sweeping wide angles of your entire lot, followed by tight, clear close-ups of every single scratch, crack, or dent. Very few storm claims require less than 500 pictures, and providing too much proof is impossible.
- Capture the surrounding area: Photograph fallen neighborhood trees, shattered street signs, or hail melting on your lawn. This builds an undeniable record that a severe weather event hit your exact coordinates.
The Claims Cafe Advantage: Staff adjusters are notorious for blaming storm-related roof leaks on “old age” or lack of maintenance. Claims Cafe uses precise documentation strategies to link your structural damage directly to the storm’s date and time, blocking the carrier’s favorite denial tactics.
Prevent Further Damage (Mitigation)
Your policy legally binds you to take immediate, reasonable steps to prevent secondary weather damage to the property.
- Make temporary repairs: Install emergency roof tarps over breaches, board up shattered windows, and clear standing water if it is safe to do so.
- Never make permanent repairs: Do not allow a contractor to install a brand-new roof or rebuild walls until the insurance company has officially inspected and documented the damage and agreed to the scope.
- Save all receipts: Retain every invoice for tarps, plywood, emergency tools, and safety equipment. Create a log of your time and fuel used. These mitigation costs are normally reimbursable.
The Claims Cafe Advantage: Balancing temporary fixes without accidentally covering up critical evidence is a tightrope walk. We communicate with your emergency mitigation team to make sure your home stays protected from Florida’s daily downpours without destroying the proof needed for your payout.
Start the Claim Quickly and Smartly
Major storms impact entire communities simultaneously, meaning insurance adjusters and phone lines get backed up almost instantly. You should act fast to avoid getting buried at the bottom of the pile.
- Contact your insurer right away: Provide the exact date and time of the storm and a basic summary of visible damage. Request a full copy of your policy jacket immediately.
- Know your specific deductibles: Deductibles vary widely based on the cause of damage. A standard deductible for an isolated thunderstorm might be a flat $1,000, while a specialized hurricane deductible might require you to pay 2% to 10% of your home’s total insured value out of pocket before coverage kicks in.
The Claims Cafe Advantage: The initial phone call sets the tone for your entire claim. Insurance representatives watch for specific keywords to shift your claim into a higher-deductible category. We handle the carrier communications directly, protecting you from costly technical mistakes.
Avoid “Storm Chasers” and Get Independent Estimates
Never rely solely on the insurance company’s captive adjuster to decide what it costs to rebuild your life. At the same time, you must protect yourself from predators.
- Beware of out-of-state door knockers: Avoid out-of-state “storm chasers” who swarm neighborhoods after a disaster offering quick fixes. Only deal with local, licensed, bonded, and insured organizations with verifiable regional references.
- Get your own advocate: Have a licensed public adjuster inspect the claim independently and write a comprehensive, line-item repair estimate based on real-world local labor and material costs.
Don’t Fight the Insurance Giant Alone
Insurance companies send their own adjusters whose primary goal is to close files quickly and minimize payouts for the company’s bottom line. They routinely miss structural shifting, ignore micro-fissures in roofing tiles, and write inadequate estimates that leave you unable to afford a proper rebuild.
You deserve equal representation. By working with a Claims Cafe public adjuster, you bring in a local, licensed expert whose only loyalty is to you. We write an exhaustive, independent repair estimate, handle the frustrating corporate phone calls, and negotiate fiercely to secure the full financial recovery you need to make your home whole again.